Disability Insurance That Protects Your Income
Your ability to earn an income supports almost everything else in your financial life. Disability insurance can help replace part of that income when a sickness or injury keeps you from working.
We’ll help you understand what you already have, where a meaningful gap may exist, and whether individual disability insurance makes sense for you.
How Much of Your Income Actually Needs Protecting?
Disability insurance is not about replacing your entire income in every case. It's about protecting the financial needs that would still be there if you couldn't work.
Your Financial Needs
Monthly expenses and financial obligations that would continue if you couldn't work.
What's Already There
Employer coverage, sick leave, savings, investments, a spouse's income, and other resources.
Your Potential Gap
The portion of your income that may still need protection.
Everyone's situation is different. The goal isn't to replace every dollar of income. It's to make sure you can still take care of what matters most if you're unable to work.
Already Have Disability Insurance Through Work? Perfect. Let's Start There.
Employer-provided disability insurance can be valuable, and there's no reason to ignore coverage you already have. The first step is understanding what it would actually provide if a sickness or injury kept you from working.
Look at the amount of income it could replace, whether there's a monthly benefit limit, how long benefits could continue, and whether the benefits may be taxable. It's also worth understanding what happens to the coverage if you change jobs or leave your employer.
Once we know what your workplace coverage actually does, we can determine whether it leaves a gap worth filling with an individual policy.
What should I check?
| How much would it actually pay?
| How long could benefits continue?
| Could the benefits be taxable?
| What happens if I leave my job?
A Disability Policy Should Work the Way You Expect It To
Two policies can offer the same monthly benefit and still provide very different protection. The differences that matter most aren't always obvious from the quote.
What Does the Policy Consider Disabled?
Being unable to do your regular job isn't always the same as being unable to work at all. The policy's definition of disability helps determine when you can qualify for benefits and whether working in another capacity could affect them.
You don't need to memorize insurance terminology, but you should understand what your policy expects before you buy it.
What If You Can Still Work—Just Not Like Before?
A sickness or injury doesn't always leave someone completely unable to work. You might return with reduced hours, different duties or lower earnings.
Some policies can provide a partial benefit in situations like these. You'll often hear this called partial or residual disability coverage. The details vary, but the important question is simple: what happens when your disability isn't all or nothing?
What Determines the Price of Disability Insurance?
When I explain disability insurance to clients, I often use a four-leaf clover. Each leaf represents one of the four choices that helps determine both what the policy protects and what it costs.
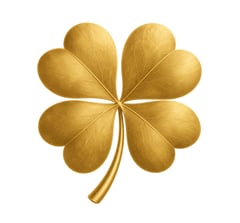
How Much It Pays
Benefit Amount
When Benefits Begin
Elimination Period
How Long Benefits Last
Benefit Period
What Else Matters to You
Optional Features & Riders
These four choices work together to determine both the protection and the price. The goal isn't to load a policy with every available feature. It's to decide which ones actually matter for your situation.
When Your Income Is Tied to a Business, There May Be More to Protect
For a business owner, personal income is only part of the picture. A disability can also affect expenses, loan obligations, ownership agreements or a business that depends heavily on your ability to work.
That doesn't mean every business owner needs another policy. It means we should separate the personal income problem from the business problem and determine what, if anything, needs protecting in each.
The Questions May Be Different
| How would my household income be affected?
| Could the business continue meeting its obligations?
| Are there loans or agreements that need to be considered?
| Is the business unusually dependent on me?
Having Disability Insurance Isn't the Same as Having Your Income Protected
One client came to me with disability insurance already in place through his employer. He earned a base salary plus commissions, and at first glance, having workplace coverage sounded like a good start.
But when we looked at what the plan actually covered, we found an important gap: his employer's disability benefit was based only on his base salary, while his commissions made up the other 75% of his income.
That mattered because his family depends heavily on what he actually earns—not just his much smaller base salary. We helped him put an individual disability policy in place to protect a large part of that gap.
Sometimes the most important part of disability planning isn't buying more coverage. It's understanding what the coverage you already have will actually do.
"His workplace coverage protected his base salary—but commissions made up the other 75% of his income."
The policy wasn't the problem.
The unprotected income was.
Founder | Woolley & Woolley Insurance Group
Ready to Figure Out What Makes Sense for You?
Whether you already have disability insurance through work, have an individual policy, or are starting from scratch, we can help you understand what's protected, where a meaningful gap may exist, and the options that make sense for you.
You'll never be pressured into the biggest policy or to add every available feature. My goal is to make sure you understand your options so you can make a confident decision.
Additional Questions About Protecting Your Income
How much disability insurance do I actually need?
Enough to protect the income your household genuinely depends on—not necessarily the maximum amount you can buy.
Start with the bills and financial commitments that would continue if a sickness or injury kept you from working. Then look at savings, a spouse's income, disability coverage through work and other resources you could realistically use.
What's left is the gap we're trying to solve. From there, we can determine how much of that gap makes sense to insure.
I have disability insurance through work. Do I need my own policy too?
Maybe, but don't assume you need another policy until you understand the one you already have.
Find out how much it would actually pay, what income is included, how long benefits could continue, whether benefits may be taxable, whether there's a maximum monthly benefit, and what happens to the coverage when you leave your employer.
Sometimes workplace coverage does a good job. Sometimes it leaves a meaningful gap. As you've seen from the real example above, even having “60% disability coverage” doesn't necessarily mean 60% of everything you earn is protected.
What's the difference between short-term and long-term disability insurance?
The biggest difference is how long the coverage is designed to help and how quickly it starts paying.
Short-term disability is generally designed for shorter disabilities and typically has a shorter waiting period. Long-term disability is designed for disabilities that last much longer and, depending on the policy, benefits may potentially continue for years.
Your savings and other resources matter here too. If you can comfortably handle the first 3-6 months yourself, protecting against a disability lasting several years may be the bigger concern.
What does own-occupation disability insurance actually mean?
It describes how the policy looks at your ability to perform your occupation, but “own occupation” by itself doesn't tell you everything you need to know.
Definitions can differ between policies. What matters is what your actual contract considers a disability, how your occupation is defined, and what happens if you're able to work in another capacity or occupation.
You don't need to become an expert in disability-policy language. This is one of the areas where I can help you understand what you're actually buying before you choose a policy.
Are disability insurance benefits taxable?
Sometimes. It largely depends on who paid the premiums and whether those premiums were paid with pre-tax or after-tax dollars.
For example, if your employer pays the premium, disability benefits are generally taxable. If you pay the entire premium yourself with after-tax dollars, benefits are generally not included in your taxable income. Arrangements where you and your employer share the cost can be more complicated.
That's one reason a workplace plan promising to replace a certain percentage of income may not leave you with that same percentage available to spend.
Can I get disability insurance if I'm self-employed?
Yes. Being self-employed doesn't prevent you from buying individual disability insurance.
In fact, not having an employer disability plan can make understanding your personal income protection especially important.
Business owners may also have expenses, loans or other business obligations that create a separate problem if they become disabled. We look at personal income protection and business needs separately rather than assuming one policy should solve everything.
Does disability insurance cover me if I lose my job or get laid off?
No. Disability insurance is not unemployment insurance.
Disability insurance is designed to provide benefits when a sickness or injury causes you to meet the policy's definition of disability. Simply losing your job, being laid off or having difficulty finding another job does not make you disabled.
This distinction matters because disability insurance is protecting your ability to work and earn income, not guaranteeing employment.
Can I still receive disability benefits if I'm able to work part-time?
Potentially. Being disabled doesn't always mean you're completely unable to work.
Some policies can provide partial benefits when a sickness or injury allows you to continue working but causes you to lose income, reduce your hours or change what you're able to do at work. You may hear this called partial or residual disability coverage.
The details vary between policies, so this is another area where we want to understand how the coverage actually works rather than relying only on the name of the feature.
Have a Question We Didn't Answer?
Whether you're reviewing coverage you already have or considering disability insurance for the first time, I'm happy to help you sort through it.